Blog

  • ITR-4 Filing Guide AY 2025-26 – Presumptive Taxation (44AD, 44ADA, 44AE) with Examples

    1. What is ITR-4?

    ITR-4 is for individuals, HUFs, and partnership firms (other than LLPs) who opt for presumptive taxation under:

    • Section 44AD – Small businesses
    • Section 44ADA – Professionals
    • Section 44AE – Transporters

    👉 This return is commonly called Sugam ITR and is designed for small taxpayers.


    2. Who Can File ITR-4?

    ✅ Resident Individual / HUF / Partnership firm (not LLP)
    ✅ Business turnover up to ₹2 crore (44AD)
    ✅ Professional receipts up to ₹50 lakh (44ADA)
    ✅ Transporter with ≤10 vehicles (44AE)

    ❌ Not eligible if:

    • Income > ₹50 lakh
    • Capital gains, foreign income, agricultural income > ₹5,000
    • Director in company, investing in unlisted shares
    • Want to claim loss carry-forward

    3. Presumptive Income Rules

    (A) Business – Sec 44AD

    • Presumed profit = 8% of turnover (if received in cash)
    • Or 6% if receipts are through bank/UPI/cheque
    • Turnover limit: ₹2 crore

    (B) Professionals – Sec 44ADA

    • Presumed profit = 50% of gross receipts
    • Limit: ₹50 lakh

    (C) Transporters – Sec 44AE

    • Presumed profit = ₹1,000 per ton per month (heavy vehicles) OR
    • ₹7,500 per vehicle per month (other vehicles)
    • Limit: 10 vehicles

    👉 In presumptive taxation, no need to maintain books of accounts.


    4. Income Tax Slabs (AY 2025-26)

    (A) Old Regime (with deductions like 80C, HRA, etc.)

    • 0 – ₹2.5L → Nil
    • ₹2.5L – ₹5L → 5%
    • ₹5L – ₹10L → 20%
    • ₹10L → 30%

    Rebate u/s 87A: If total income ≤ ₹5L → Tax = Nil


    (B) New Regime (default – Sec 115BAC)

    Revised slabs (w.e.f. AY 2024-25 onwards):

    • 0 – ₹3L → Nil
    • ₹3L – ₹6L → 5%
    • ₹6L – ₹9L → 10%
    • ₹9L – ₹12L → 15%
    • ₹12L – ₹15L → 20%
    • ₹15L → 30%

    Rebate u/s 87A: If total income ≤ ₹7L → Tax = Nil


    5. Step-by-Step Filing Process (Online – Income Tax Portal)

    1. Login at incometax.gov.in
    2. Go to e-File > Income Tax Return > File ITR
    3. Select:
      • AY = 2025-26
      • ITR Form = ITR-4
      • Filing Type = Original/Revised
    4. Fill sections:
      • Personal info (PAN, Aadhaar, bank details)
      • Income details → presumptive income (44AD/44ADA/44AE)
      • Other income (FD interest, savings interest)
      • Deductions (if opting for Old Regime)
      • Taxes paid (TDS/TCS as per Form 26AS & AIS)
    5. Choose Tax Regime (Old/New)
    6. Preview & Submit return
    7. e-Verify using Aadhaar OTP, Netbanking, or DSC

    6. Example Calculations

    Example 1: Businessman (44AD)

    • Turnover: ₹40,00,000
    • Mode: All digital (6%)
    • Presumed Income = 6% × 40,00,000 = ₹2,40,000

    👉 Tax under Old Regime: Nil (below ₹2.5L)
    👉 Tax under New Regime: Nil (below ₹3L)

    ✅ No tax payable


    Example 2: Professional (44ADA)

    • Gross Receipts: ₹20,00,000
    • Presumed Income = 50% = ₹10,00,000

    👉 Old Regime:

    • Tax = ₹1,12,500 (after slab benefits, before cess, assuming 80C = 1.5L)

    👉 New Regime:

    • Tax = ₹52,500 (lower, because standard deduction + slab benefit)

    ✅ Better to choose New Regime


    Example 3: Transporter (44AE)

    • 5 small vehicles, owned full year
    • Presumed Income = 5 × 12 × ₹7,500 = ₹4,50,000

    👉 Old Regime: Nil (rebate 87A up to ₹5L)
    👉 New Regime: Nil (rebate up to ₹7L)

    ✅ No tax payable


    7. Precautions While Filing

    ⚠️ Ensure turnover/receipts are correctly reported (cross-check with GST if applicable).
    ⚠️ Verify TDS entries from Form 26AS & AIS.
    ⚠️ If you opt out of presumptive scheme, you can’t re-enter for 5 years (44AD rule).
    ⚠️ Keep proof of digital payments to claim 6% rate in 44AD.
    ⚠️ Choose regime carefully – once chosen, binding for the year.


    8. Final Tips

    • Use ITR-4 only if presumptive scheme applies.
    • If income is slightly higher than exemption, consider investments under Old Regime.
    • Compare both regimes before filing.
    • Always e-verify your return to avoid invalidation.

    1. Special Advantage of Presumptive Scheme

    Under the presumptive taxation scheme:

    • Section 44AD (Business):
      Government assumes 92% turnover is expense + savings, and only 8% (or 6% if digital) is treated as taxable profit.
      👉 This means 92% of turnover is treated as expenses without needing receipts, vouchers, or books of accounts.
    • Section 44ADA (Professionals):
      Government assumes 50% of gross receipts are expenses.
      👉 Only 50% is taxable income, even if actual expenses are less.
      👉 You don’t have to maintain invoices, rent slips, travel logs, etc. for deductions.
    • Section 44AE (Transport):
      Profit is fixed per vehicle, regardless of actual diesel, maintenance, driver salary, EMI etc.
      👉 All such expenses are deemed included in presumptive scheme.

    ⚠️ Important: If you declare income less than presumptive %, you must:

    • Maintain books of accounts, AND
    • Get them audited u/s 44AB,
      which defeats the simplicity.

    2. Example – Professional (Sec 44ADA)

    • Gross Receipts: ₹30,00,000
    • Expenses (travel, rent, staff salary, laptop, utilities etc.) not tracked with bills.
    • Under normal system, you must maintain receipts, and show actual profit.

    👉 Under Presumptive (44ADA):

    • 50% presumed expenses = ₹15,00,000 (without receipts)
    • 50% profit = ₹15,00,000 (taxable income)

    📌 Even if your actual expenses are only ₹5 lakh, you still get the benefit of ₹15 lakh expenses allowed automatically.


    3. Example – Business (Sec 44AD)

    • Turnover: ₹80,00,000
    • If 100% digital → Presumed Profit = 6% × 80L = ₹4.8L
    • Deemed Expenses = ₹75.2L (no proof needed)

    4. Practical Benefits

    No Receipts / Proof Required – Rent, fuel, internet, staff salaries, repairs etc. are presumed.
    No CA Audit – Unless you declare lower profit.
    No Complex Books – Only basic records of turnover/receipts.
    Tax Savings – You may end up showing higher expenses than actually incurred.


    5. Precautions

    ⚠️ If you have very high actual expenses (say >50% in profession), presumptive scheme may increase taxable profit compared to actuals.
    ⚠️ Once you exit presumptive (44AD), you can’t rejoin for next 5 years.
    ⚠️ Professional (44ADA) – 50% deemed expense is mandatory, you cannot show lower (unless you keep books + audit).


    ✅ So the “50% expense without receipts” point applies mainly to professionals (44ADA).
    For businesses (44AD), it’s roughly 92% expenses without receipts (only 8%/6% profit taxed).


  • Top 25 Excel Formulas Every Accountant Should Know (With Clear Examples)

    In today’s business world, accountants rely heavily on Microsoft Excel to manage financial data, prepare reports, and analyze numbers quickly. While anyone can enter data into Excel, mastering the right formulas is what makes an accountant truly efficient and accurate. From simple calculations like SUM and AVERAGE to advanced ones like VLOOKUP, IF, and INDEX-MATCH, these formulas save time, reduce errors, and improve decision-making.

    In this guide, we’ll explore the Top 25 Excel formulas every accountant must know, along with practical examples to help you apply them in real-life accounting tasks.

    Below, I use a simple sample table called Transactions (Excel Table) with columns:
    Date | Voucher | Account | Customer | Amount | Tax | Status | Salesperson

    Tip: Turn your data into a Table with Ctrl + T and use structured references (e.g., Transactions[Amount]).


    1) SUM

    What it does: Adds numbers.

    =SUM(Transactions[Amount])
    

    Quickly totals all amounts.


    2) SUMIFS

    What it does: Sum with multiple conditions (e.g., date range + account).

    =SUMIFS(Transactions[Amount], Transactions[Account], "Sales", Transactions[Date], ">="&DATE(2025,4,1), Transactions[Date], "<="&DATE(2025,6,30))
    

    Use case: Q1 sales only; or sum by customer & status.


    3) COUNTIFS

    What it does: Counts rows meeting multiple criteria.

    =COUNTIFS(Transactions[Status], "Paid", Transactions[Account], "Sales")
    

    How many paid sales invoices?


    4) AVERAGEIFS

    What it does: Average with multiple criteria.

    =AVERAGEIFS(Transactions[Amount], Transactions[Account], "Sales", Transactions[Status], "Paid")
    

    Average paid invoice value.


    5) IF

    What it does: Logical test → value if true/false.

    =IF([@Status]="Overdue","Follow-up","OK")
    

    Flags overdue invoices.


    6) IFS

    What it does: Chain multiple conditions neatly.

    =IFS([@Amount]>=100000,"High",[@Amount]>=25000,"Medium",TRUE,"Low")
    

    7) IFERROR

    What it does: Handles errors gracefully.

    =IFERROR([@[Amount]]/[@[Tax]],0)
    

    Avoids #DIV/0! when tax is zero.


    8) XLOOKUP

    What it does: Modern, flexible lookup (left/right, exact by default).

    =XLOOKUP("CUST-007", Customers[CustID], Customers[GSTIN], "Not found")
    

    Also return multiple columns by selecting a multi-column return array.


    9) VLOOKUP (Legacy but common)

    What it does: Vertical lookup (be careful with column index).

    =VLOOKUP("CUST-007", Customers!A:H, 5, FALSE)
    

    Prefer XLOOKUP where available.


    10) INDEX + MATCH

    What it does: Powerful two-step lookup (works leftward; great for 2D lookups).

    =INDEX(Rates[Rate], MATCH([@Account], Rates[Account], 0))
    

    Two-way example (row & column):

    =INDEX(PivotArea, MATCH("Sales", RowLabels, 0), MATCH("Apr-2025", ColLabels, 0))
    

    11) SUMPRODUCT

    What it does: Conditional math without helper columns; weighted averages.

    =SUMPRODUCT((Transactions[Account]="Sales")*(Transactions[Status]="Paid")*Transactions[Amount])
    

    Weighted average tax rate:

    =SUMPRODUCT(Transactions[Amount], Transactions[Tax]) / SUM(Transactions[Amount])
    

    12) ROUND, ROUNDUP, ROUNDDOWN

    What they do: Control rounding for reports, invoices, GST.

    =ROUND([@Amount]*1.18, 0)      // nearest rupee
    =ROUNDUP([@Amount]*1.18, 0)    // always up
    =ROUNDDOWN([@Amount]*1.18, 0)  // always down
    

    13) ABS

    What it does: Absolute value—useful for variance and adjustments.

    =ABS([@Amount]-[@Budget])
    

    14) EOMONTH & EDATE

    What they do: Month math—closing, aging buckets.

    =EOMONTH([@Date], 0)            // month-end of transaction month
    =EDATE([@Date], 3)              // +3 months
    

    15) DATE, YEAR, MONTH, DAY

    What they do: Build and dissect dates (reporting, grouping).

    =DATE(2025,4,1)
    =YEAR([@Date])    // 2025
    =MONTH([@Date])   // 4
    =DAY([@Date])     // 1
    

    16) DATEDIF

    What it does: Precise gaps (undocumented but reliable).

    =DATEDIF([@JoiningDate], TODAY(), "Y")   // years of service
    

    Other units: "M", "D", "YM" (months ignoring years), "MD".


    17) NETWORKDAYS / NETWORKDAYS.INTL

    What they do: Business days between dates (exclude weekends/holidays).

    =NETWORKDAYS([@InvoiceDate], [@DueDate], HolidayList[Date])
    

    NETWORKDAYS.INTL lets you define weekend pattern (e.g., Friday–Saturday).


    18) WORKDAY / WORKDAY.INTL

    What they do: Add business days to a date (promised date / SLAs).

    =WORKDAY([@InvoiceDate], 7, HolidayList[Date])   // due date after 7 workdays
    

    19) TEXT

    What it does: Format numbers/dates to text (report labels, exports).

    =TEXT([@Date], "dd-mmm-yyyy")
    =TEXT([@Amount], "₹#,##0.00")
    

    20) TEXTJOIN / CONCAT

    What they do: Build strings (invoice titles, addresses).

    =TEXTJOIN(", ", TRUE, [@Customer], [@City], [@State])
    

    Skips blanks with the TRUE argument.


    21) FILTER (Dynamic arrays)

    What it does: Extract rows matching criteria—live query!

    =FILTER(Transactions, (Transactions[Account]="Sales")*(Transactions[Status]="Paid"))
    

    Great for creating dynamic sub-ledgers.


    22) UNIQUE

    What it does: Distinct lists (customers, accounts) for validation and pivots.

    =UNIQUE(Transactions[Customer])
    

    23) SUBTOTAL

    What it does: Aware of filters; ignores hidden rows (choose function code 9/109 for SUM).

    =SUBTOTAL(109, Transactions[Amount])   // SUM visible only
    

    24) NPV, IRR, PMT (Finance Trio)

    What they do: Core finance math for accountants.

    • NPV – Net Present Value:
    =NPV(10%, C2:C7) + C1
    

    (10% discount rate; C1 is initial outflow if entered as a positive value—add it separately.)

    • IRR – Internal Rate of Return:
    =IRR(C1:C7)
    
    • PMT – Loan EMI:
    =PMT(10%/12, 60, -500000)
    

    (10% annual, 60 months, ₹5,00,000 principal.)

    For irregular timings, use XNPV/XIRR.


    25) SORT

    What it does: Sort ranges dynamically (often used with FILTER/UNIQUE).

    =SORT(FILTER(Transactions, Transactions[Status]="Unpaid"), 1, 1)
    

    Sorts by first column ascending.


    Practical Mini-Scenarios

    A) Aging Bucket (30/60/90+)

    =IFS([@DaysDue]<=30,"0–30",[@DaysDue]<=60,"31–60",[@DaysDue]<=90,"61–90",TRUE,"90+")
    

    B) Month-End Provisioning

    =IF(EOMONTH([@Date],0)=TODAY(),"Provision","")
    

    C) Sales by Rep (Dynamic report)

    =LET(
     data, Transactions,
     sales, FILTER(data, data[Account]="Sales"),
     SUMIFS(sales[Amount], sales[Salesperson], H2)
    )
    

    (Using LET to make it readable; optional but powerful.)


    Common Pitfalls & Pro Tips

    • Dates: Use DATE(yyyy,mm,dd) inside criteria (avoid text dates).
    • SUMIFS text criteria: Use operators with &">="&DATE(2025,4,1).
    • Rounding: Always round before tax filings/exports to prevent paise mismatches.
    • Dynamic Arrays: If results “spill,” ensure cells below/right are empty.
    • Lookups: Prefer XLOOKUP with a clear not-found message: =XLOOKUP(A2, Map[Code], Map[Name], "No match")

    Quick Reference (What to use when)

    • Conditional totals/counts: SUMIFS, COUNTIFS, SUMPRODUCT
    • Lookups: XLOOKUP (or INDEX+MATCH)
    • Dates & working days: EOMONTH, EDATE, NETWORKDAYS, WORKDAY
    • Cleanup/formatting: TEXT, TEXTJOIN, rounding functions
    • Dynamic reporting: FILTER, UNIQUE, SORT, SUBTOTAL
    • Finance: NPV, IRR, PMT

  • NCERT Textbook Controversies: What’s Changing and Why It Matters

    Education is never just about learning facts; it’s about shaping how young minds understand the world around them. In India, this idea is at the forefront of debates surrounding the recent changes in NCERT (National Council of Educational Research and Training) textbooks. From renaming books with culturally rooted titles to removing or revising chapters on the Mughal dynasty and Delhi Sultanate, these changes have sparked widespread discussion on education, ideology, and identity.


    New Names, New Identity

    One of the most visible changes has been the introduction of new, culturally inspired titles. Books now come with names such as Mridang, Ganit Prakash, and Poorvi. These terms draw from India’s traditional heritage—musical instruments, ragas, and indigenous knowledge systems.

    The intention, as explained under the National Education Policy (NEP) 2020 and National Curriculum Framework 2023, is to “decolonize” the curriculum and give students a stronger sense of cultural belonging. Proponents argue this move is essential to instill pride in Indian traditions. Critics, however, caution that such naming may not reflect the diversity of India and could impose cultural symbols not equally familiar to all regions.


    History Rewritten?

    Another significant area of controversy is the removal of chapters related to the Mughal dynasty and Delhi Sultanate in middle-school history books. Instead, there is a greater emphasis on ancient Indian dynasties, indigenous scientific traditions, and spiritual geography.

    According to NCERT officials, this is part of a broader “rationalization process” aimed at reducing curriculum overload and avoiding content duplication—an effort that began during the pandemic. Yet, critics argue that this risks oversimplifying or even distorting India’s diverse history, depriving students of a fuller understanding of the nation’s past.


    Why It Matters

    These changes go far beyond the pages of a textbook. They raise important questions about the role of education:

    • Should textbooks highlight national pride and cultural heritage, or should they prioritize balanced representation of all historical eras?
    • Can the process of decolonizing the curriculum strengthen identity, or might it inadvertently limit exposure to India’s pluralistic history?
    • What long-term impact will these shifts have on students preparing for competitive exams, higher studies, and global engagement?

    For parents, teachers, and policymakers, the debate underscores the enormous power that curriculum decisions hold in shaping young minds.


    Conclusion

    The NCERT textbook revisions are not just academic adjustments—they are reflections of India’s evolving educational philosophy and political climate. Whether viewed as necessary corrections or controversial omissions, these changes will influence how an entire generation sees India’s past, present, and future.


    Disclaimer: This article is for informational and educational purposes only. It summarizes ongoing debates around NCERT textbooks without taking a political or ideological position. For official updates, readers should consult NCERT and Ministry of Education announcements.


  • Fitch Affirms India’s Credit Rating – Growth Story Continues Even After Tariff Shocks

    Global rating agency Fitch Ratings has recently reaffirmed India’s sovereign credit rating at ‘BBB-’ with a Stable Outlook. This means India continues to hold its position at the lowest investment-grade rating, which is crucial for international investors, foreign direct investment (FDI), and overall global confidence in India’s economy.

    Despite ongoing trade risks, global economic slowdown, and geopolitical tensions, Fitch has recognized India’s strong growth prospects, robust domestic demand, and effective monetary policy as key reasons for maintaining the rating.


    What is a Credit Rating?

    A sovereign credit rating is an independent evaluation of a country’s ability to repay its debts. It directly impacts:

    • Foreign Investment inflows
    • Government borrowing costs
    • Global trade competitiveness

    India’s ‘BBB-’ rating is the lowest investment-grade category, but still important because it keeps India in the pool of investible nations.


    Why Did Fitch Affirm India’s Rating?

    1. Strong Economic Growth – India remains the fastest-growing major economy, with GDP growth expected above 6% despite global challenges.
    2. Domestic Demand – Rising consumption and infrastructure spending are driving growth.
    3. Government Reforms – Initiatives like GST, PLI schemes, digitalization, and Make in India provide long-term stability.
    4. Stable Financial Sector – NPA ratios are falling, banking recapitalization is effective, and credit growth is improving.
    5. Monetary Policy Management – The RBI’s inflation control measures have maintained relative stability.

    Key Trade Risks Highlighted by Fitch

    1. Global Trade Slowdown – Weak demand in the US and EU can affect India’s exports.
    2. Geopolitical Tensions – Conflicts and supply-chain disruptions (e.g., Red Sea crisis, Russia-Ukraine war) raise risks.
    3. China Factor – China’s slowdown impacts regional trade and commodity prices, which indirectly affect India.
    4. High Public Debt – India’s debt-to-GDP ratio (~83%) remains high compared to peers, which keeps its rating from being upgraded.

    Impact on India

    Positive Impacts

    • Global investors will remain confident about India’s long-term prospects.
    • Indian Rupee stability due to continued foreign inflows.
    • Lower borrowing costs for government and corporates in international markets.

    Concerns

    • High fiscal deficit limits fiscal flexibility.
    • Any external shock (oil prices, US interest rate hikes) could pressure India’s economy.
    • Limited export growth could affect trade balance.

    Real Examples

    • 2020 downgrade threats: During the pandemic, there were concerns India could fall into “junk” rating, but policy reforms and fast recovery saved it.
    • Moody’s upgrade (2021): Moody’s had earlier revised India’s outlook from “Negative” to “Stable” citing resilience. Fitch’s affirmation follows the same confidence.
    • FDI inflows (2023–24): India attracted record FDI in IT, manufacturing, and green energy sectors, showing rating agencies trust in long-term fundamentals.

    Q&A for Students (Exam Preparation)

    Q1. What does a sovereign credit rating signify?
    A1. It shows a country’s ability to repay its external debt and impacts investor confidence.

    Q2. What is India’s current Fitch rating?
    A2. BBB- with a Stable Outlook (investment-grade rating).

    Q3. Why is the rating not upgraded despite strong growth?
    A3. Because of high public debt (~83% of GDP) and fiscal deficit concerns.

    Q4. Which factors supported Fitch’s decision?
    A4. Strong GDP growth, domestic demand, banking stability, and government reforms.

    Q5. What are the risks that could affect India’s rating?
    A5. Global trade slowdown, geopolitical tensions, and external shocks (oil, US rates).

    Q6. How does a credit rating impact FDI?
    A6. A good rating ensures investors’ confidence and encourages long-term capital inflows.

    Q7. Who are the “Big Three” credit rating agencies?
    A7. Fitch Ratings, Moody’s, and Standard & Poor’s (S&P).

    Q8. What is the difference between “Stable Outlook” and “Positive Outlook”?
    A8. Stable = no change expected soon, Positive = chances of upgrade in the near future.

    Q9. Which sector in India is most vulnerable to trade risks?
    A9. Export-driven sectors like textiles, IT services, and gems & jewelry.

    Q10. Can India’s rating improve in the future? If yes, how?
    A10. Yes, if fiscal deficit reduces, debt-to-GDP falls, and exports improve consistently.


    Conclusion

    Fitch’s affirmation of India’s rating highlights a balanced view: confidence in India’s growth story but caution on fiscal management and global risks. For students and professionals, this event underlines the importance of macroeconomic stability, credit ratings, and international trade linkages in shaping India’s financial future.


    📌 Disclaimer

    The information provided in this article is for educational and informational purposes only. It is based on publicly available reports and analysis at the time of writing. This should not be considered financial or investment advice. Readers are advised to conduct their own research or consult a qualified financial advisor before making any investment or policy-related decisions.


  • India’s Banking Sector Opens Up to Foreign Investors: What It Means for Finance & Economy

    India’s banking industry has long been a fortress, heavily regulated and largely protected from foreign players. But recent policy signals suggest a gradual opening to foreign investors. This shift could transform India’s financial sector — if handled wisely.


    Why Is India Opening Up Its Banking Sector?

    1. Capital Infusion Needs – Many Indian banks, especially public sector banks (PSBs), need fresh capital to meet Basel III norms and fund credit growth. Foreign capital can help bridge the gap.
    2. Global Integration – As India aims for a $5-trillion economy, opening its banking sector builds investor confidence and aligns it with international practices.
    3. Fintech Revolution – With UPI, AI-driven lending, and digital banking growing rapidly, foreign players want to be part of India’s fintech ecosystem.
    4. Insurance & NBFC Precedent – India has already allowed foreign stakes in insurance (FDI up to 74%) and NBFCs. Extending this to banks is the next step.

    Recent Developments & Real Examples

    • Yes Bank (2020–21): During its crisis, global private equity firms like Carlyle Group and Advent International invested in Yes Bank. This showed India’s willingness to allow foreign capital in distressed banks.
    • IDBI Bank (2022): The Indian government invited foreign investors (including sovereign wealth funds and global banks) to bid for stakes in IDBI Bank, signaling openness to foreign strategic investment.
    • LIC Reclassification (2025): By tweaking how Life Insurance Corporation (LIC) is classified, the government paved the way for greater foreign stakes in banks where LIC holds large shares.
    • HSBC & Citi in India: Foreign banks like HSBC, Standard Chartered, and Citi already operate in India but at limited scale. Recent reforms may allow them to expand operations or buy larger stakes in Indian lenders.

    Potential Impacts

    1. On Banks

    • Positive: Infusion of capital, better global practices (risk management, governance).
    • Example: After Carlyle’s stake in Yes Bank, the bank improved its digital offerings and NPA management.
    • Risk: Increased foreign influence in decision-making during crises.

    2. On Fintech & Startups

    • Positive: More foreign partnerships.
    • Example: DBS Bank Singapore merged with Lakshmi Vilas Bank in 2020, showing how foreign institutions can strengthen weak Indian banks while tapping fintech collaborations.

    3. On Consumers

    • Positive: More competition = better services and innovative products.
    • Example: HSBC India’s digital wealth management services raised the bar for customer experience.
    • Risk: Foreign banks may focus on elite/urban markets, leaving rural India underserved.

    4. On Economy

    • Positive: Stronger capital base boosts lending, growth, and investor confidence.
    • Risk: Over-reliance on foreign capital could make India vulnerable to global shocks (like sudden capital outflows).

    Challenges Ahead

    • Regulatory Balance: RBI must safeguard sovereignty while encouraging investment.
    • Political Resistance: Banking reforms face pushback since banks are tied to economic independence.
    • Level Playing Field: Domestic banks need protection from foreign dominance.

    Conclusion

    India’s cautious opening of its banking sector to foreign investors is a strategic move. Done carefully, it could bring capital, innovation, and global expertise while keeping domestic control intact. Real-world cases like Yes Bank’s revival, DBS-LVB merger, and IDBI stake sale highlight how this change is already reshaping India’s banking landscape.


    10 Practice Q&A for Students

    Q1. Why is India allowing more foreign investment in banks?
    A1. To raise capital, integrate with global markets, and improve governance.

    Q2. Which distressed bank attracted foreign PE investors like Carlyle and Advent?
    A2. Yes Bank.

    Q3. Which Indian bank’s stake sale was opened to foreign sovereign funds and banks in 2022?
    A3. IDBI Bank.

    Q4. Which Singapore-based foreign bank merged with Lakshmi Vilas Bank in 2020?
    A4. DBS Bank.

    Q5. Why was LIC’s classification changed recently?
    A5. To facilitate foreign investment in banks where LIC is a major shareholder.

    Q6. Name two foreign banks already present in India.
    A6. HSBC and Standard Chartered.

    Q7. What benefit will consumers see from foreign entry into banking?
    A7. More competition, better services, and innovative products.

    Q8. What is one risk of allowing too much foreign investment?
    A8. Excessive foreign influence in decision-making and exposure to global capital shocks.

    Q9. Which regulatory body oversees foreign investment in banks?
    A9. Reserve Bank of India (RBI).

    Q10. What balance must RBI maintain in this reform?
    A10. A balance between welcoming foreign capital and protecting financial sovereignty.


  • RBI’s AI Framework for the Financial Sector: What It Means for India

    Artificial Intelligence (AI) is no longer just a buzzword—it’s becoming the backbone of financial systems worldwide. Recognizing its importance, the Reserve Bank of India (RBI) recently released a proposal for a comprehensive AI framework (named FREEAI) that aims to reshape how banks, fintechs, and regulators use artificial intelligence in the financial sector.


    What is the FREEAI Framework?

    FREEAI stands for Financial Regulation for Ethical and Efficient AI. This framework has three key pillars:

    1. Infrastructure – Building secure and scalable AI systems that can be integrated into existing banking infrastructure, payments (like UPI), and risk monitoring platforms.
    2. Governance – Setting clear rules for how AI can be developed, deployed, and audited in finance. This includes preventing bias in algorithms, ensuring transparency in decision-making, and protecting customer privacy.
    3. Risk Management – Monitoring risks such as data misuse, cybersecurity threats, or unfair lending practices caused by black-box AI models. RBI aims to set up a dedicated supervisory body for AI in finance.

    Why Did RBI Introduce This Now?

    • Explosion of Fintech in India: With UPI, digital lending, and Buy Now Pay Later (BNPL) schemes, AI-driven credit scoring and fraud detection are already widespread.
    • Global AI Race: The EU and US have recently passed regulations to govern AI in finance, and India doesn’t want to lag behind.
    • Consumer Protection: AI has improved efficiency but also raised concerns—such as biased lending decisions, automated debt collection harassment, and data misuse.

    Key Impacts of RBI’s AI Framework

    1. On Banks

    • Banks will need to audit their AI systems regularly.
    • Lending decisions (like credit scoring) must be explainable to regulators and customers.
    • Data security standards will become stricter, pushing banks to invest in compliance technology.

    2. On Fintech Startups

    • Startups using AI for instant loans, KYC verification, or fraud detection will face higher compliance costs.
    • However, this will also build trust among users and investors, helping serious fintechs scale.
    • Expect a wave of AI audit firms and compliance-as-a-service providers to emerge.

    3. On Consumers

    • Customers will benefit from fairer credit scoring models, fewer hidden biases, and better data protection.
    • Complaints related to automated lending harassment or fraud may decline once strict accountability rules are enforced.

    4. On the Economy

    • By standardizing AI in finance, India will attract more global investment in fintech, as foreign players prefer markets with regulatory clarity.
    • FREEAI will also create demand for skilled professionals in AI, data science, and compliance, boosting education and job opportunities.

    Challenges Ahead

    • Cost of Compliance: Smaller fintechs may struggle with the cost of frequent AI audits.
    • Innovation vs. Regulation: Too much regulation could slow down experimentation in AI-driven financial products.
    • Capacity Building: RBI itself will need skilled AI experts to effectively supervise the system.

    Conclusion

    RBI’s FREEAI Framework is a landmark step towards balancing innovation with responsibility in India’s financial sector. While it will add compliance pressure on banks and fintech startups, it will ultimately build trust, stability, and long-term growth. For consumers, this means safer, fairer, and more transparent digital finance.

    India has already led the world with UPI—and with FREEAI, it could set global benchmarks in AI-driven financial governance too.


    RBI’s AI Framework (FREEAI): 10 Practice Questions & Answers

    Q1. What does FREEAI stand for in the context of RBI’s new AI framework?
    A1. FREEAI = Financial Regulation for Ethical and Efficient AI.


    Q2. What are the three main pillars of the FREEAI framework?
    A2. (i) Infrastructure, (ii) Governance, (iii) Risk Management.


    Q3. Why has RBI proposed the FREEAI framework?
    A3. To ensure responsible use of AI in the financial sector, prevent risks like bias and fraud, and provide regulatory clarity for banks and fintechs.


    Q4. Which existing Indian payment system is expected to integrate AI under FREEAI?
    A4. UPI (Unified Payments Interface).


    Q5. Name two major risks of AI in finance that FREEAI seeks to address.
    A5. (i) Bias in credit scoring/lending decisions, (ii) Cybersecurity threats/data misuse.


    Q6. How will FREEAI impact fintech startups in India?
    A6. Startups will face higher compliance and audit requirements, but it will also increase user trust and investor confidence.


    Q7. Which international regions have already introduced AI regulations that influenced India’s move?
    A7. European Union (EU) and the United States (US).


    Q8. What is one key benefit of FREEAI for consumers?
    A8. Consumers will get fairer, transparent, and more accountable AI-driven financial services (like unbiased credit scoring).


    Q9. How might FREEAI affect job opportunities in India?
    A9. It will increase demand for AI, data science, and compliance professionals in the financial sector.


    Q10. What is the long-term goal of RBI’s FREEAI framework?
    A10. To balance innovation and responsibility, making India a global leader in AI-driven financial governance.


  • Top 10 Excel Interview Questions for HR Professionals (With Best Answers)

    Why Excel is a Must for HR Professionals

    In today’s data-driven workplace, HR is no longer limited to recruitment and payroll — it plays a strategic role in workforce planning, performance tracking, and decision-making. Excel is the most widely used tool in HR because it allows professionals to:

    • 📊 Manage Employee Data Efficiently – Store, clean, and organize employee records in structured formats.
    • Save Time with Automation – Use formulas, Pivot Tables, and Macros to speed up repetitive tasks like attendance, payroll, and compliance reporting.
    • 📈 Generate HR Analytics & Insights – Create dashboards and reports for attrition, hiring trends, diversity ratios, and performance analysis.
    • Ensure Accuracy in Payroll & Compliance – Minimize errors using functions, validations, and templates.
    • 💡 Support Decision-Making – Present HR metrics in charts, visuals, and summaries for management.

    Simply put, Excel is the backbone of HR MIS reporting and analytics. Whether it’s preparing salary sheets, tracking leave, analyzing attrition, or creating dashboards, Excel skills make an HR professional far more valuable and efficient.

    Let’s look at the top 10 Excel interview questions for HR profiles and how to answer them effectively.


    Top 10 Excel Interview Questions for HR Profile (With Best Answers)

    1. How do you use Excel in your HR role?

    Best Answer:
    “I use Excel to manage employee databases, track attendance, calculate payroll, generate HR MIS reports, and analyze attrition or recruitment trends. Pivot tables and charts help me quickly summarize large HR datasets for management decisions.”


    2. Which Excel functions do you frequently use in HR reporting?

    Best Answer:
    “I frequently use VLOOKUP/XLOOKUP, IF, SUMIF(S), COUNTIF(S), TEXT, CONCATENATE, LEFT/RIGHT, and DATE functions. These help in validating employee data, calculating salary components, and preparing HR dashboards.”


    3. How do you handle large employee data sets efficiently in Excel?

    Best Answer:
    “I use Pivot Tables, Filters, Conditional Formatting, and Data Validation to quickly organize and clean employee data. For repeated tasks, I also rely on Macros to automate processes like monthly payroll reports or attendance summaries.”


    4. Can you explain VLOOKUP/XLOOKUP with an HR example?

    Best Answer:
    “Suppose I have an employee ID in one sheet and need to fetch their department or salary from another sheet, I use XLOOKUP (or VLOOKUP). For example:
    =XLOOKUP(A2, Employee_IDs, Department)
    This makes it easy to map employee details across HR records.”


    5. How do you track employee attendance and leave in Excel?

    Best Answer:
    “I create a leave tracker using conditional formatting to highlight absences, late arrivals, or excess leave. I also use COUNTIF to calculate the number of days absent/present and prepare monthly reports for payroll processing.”


    6. What Excel tools would you use to prepare an HR dashboard?

    Best Answer:
    “For an HR dashboard, I use:

    • Pivot Tables & Pivot Charts for headcount, attrition, and recruitment data.
    • Slicers & Timelines for interactive reports.
    • Conditional Formatting & Sparklines to highlight KPIs.
      This gives management a clear view of HR performance metrics.”

    7. How do you ensure accuracy in HR data using Excel?

    Best Answer:
    “I apply Data Validation to restrict wrong entries (like dates, gender, department codes), use formulas like TRIM & CLEAN to remove unwanted spaces, and cross-verify data using LOOKUP formulas. This ensures accuracy in payroll and employee records.”


    8. How do you calculate employee salary components in Excel?

    Best Answer:
    “I break down salary into components (Basic, HRA, Allowances, Deductions) and use formulas like =Basic*0.40 for HRA or =Gross-Deductions for Net Salary. I also use IF conditions for tax slabs and automations for faster payroll processing.”


    9. Can you explain how Pivot Tables help in HR analytics?

    Best Answer:
    “Pivot Tables allow me to quickly summarize data such as attrition by department, recruitment by month, or gender diversity ratio. They save time compared to manual calculations and are highly useful for HR presentations.”


    10. Have you used Excel Macros or VBA in HR work?

    Best Answer:
    “Yes, I have used simple Macros to automate repetitive HR tasks such as generating monthly salary slips, attendance reports, and employee letters. This reduces manual effort and improves efficiency.”


    Excel has become an indispensable tool for HR professionals. From managing employee databases to preparing dashboards and payroll automation, Excel skills not only save time but also enhance accuracy and decision-making. In interviews, employers often assess your ability to apply Excel knowledge to real HR scenarios, so demonstrating practical examples is key.

    💡 Pro Tip:
    Don’t just memorize functions—practice them with real HR data like attendance sheets, payroll calculations, or attrition reports. If you can confidently explain how you used Excel in your previous role (or even in practice projects), you’ll stand out as a candidate who can deliver value from day one.


  • Choosing Between 1-Year and 2-Year MBA in India – Key Differences Explained

    1-Year MBA or 2-Year MBA in India? A Complete Guide for Students & Professionals

    Rohan had been working in a multinational company in Bengaluru for nearly five years. At 28, he felt his career was at a crossroads. His manager had hinted that leadership roles required “an MBA edge.” But the big question was — should he go for a 1-year MBA or the traditional 2-year MBA?

    This dilemma isn’t unique to Rohan. Thousands of young professionals in India face the same choice every year. Let’s walk through this decision, not with statistics alone, but through real-life scenarios you might relate to.


    🎓 The 2-Year MBA – The Classic Route

    Imagine Priya, a 23-year-old commerce graduate from Delhi. She had little work experience but big dreams of becoming an investment banker. She opted for a 2-year MBA at IIM Lucknow.

    Why?

    • Foundational Learning: The first year gave her a strong base in finance, marketing, HR, and operations.
    • Internship Exposure: During her summer internship, she got hands-on experience in an investment bank, which later converted into a pre-placement offer.
    • Peer Learning: Most of her classmates were freshers or had minimal work experience. Group projects, cultural fests, and case studies built her confidence.

    👉 For Priya, the 2-year MBA was perfect. It gave her time to explore different fields, build a network, and transition into her dream career.


    🚀 The 1-Year MBA – The Fast-Track Path

    Now let’s consider Arjun, 32, a senior IT consultant from Pune with 9 years of experience. He didn’t want to step away from the corporate ladder for too long, but he knew leadership roles required business acumen. He chose a 1-year MBA at ISB Hyderabad.

    Why?

    • Time Efficient: Only 12 months away from work, instead of 24.
    • Peer Group: His classmates were all mid-career professionals, making discussions more industry-focused.
    • ROI: Yes, the fee was high, but he could return to work faster and recover his investment sooner.
    • Global Recognition: Many top B-schools (ISB, IIM Ahmedabad PGPX, etc.) have strong global rankings for 1-year programs.

    👉 For Arjun, the 1-year MBA was the right fit. It helped him upgrade skills, switch roles, and return to the corporate world without losing momentum.


    ⚖️ Key Differences at a Glance

    Factor2-Year MBA1-Year MBA
    Target StudentsFresh graduates / <3 years experienceMid-career professionals (5-12 years exp.)
    Duration24 months12 months
    CurriculumFoundation + specialization + internshipIntense, specialization-focused
    NetworkingStrong, but peers mostly youngRich, with experienced professionals
    InternshipsYes (key advantage)Usually no (direct placements)
    Cost vs ROIHigher opportunity cost due to 2 years off workFaster ROI due to shorter break
    Examples in IndiaIIMs (2-year PGP), XLRI, SPJIMRISB, IIM PGPX, XLRI 1-year PGDM

    🧭 Which One Should You Choose?

    • If you are early in your career and want to explore different fields, build a strong foundation, and enjoy campus life → Go for a 2-Year MBA.
    • If you are a mid-career professional with clear goals, want a fast-track leadership boost, and can handle an intense curriculum → Opt for a 1-Year MBA.

    🌟 The Takeaway

    Both paths can transform your career — the choice depends on where you are in your journey.

    Priya needed time to explore, so the 2-year MBA was her launchpad. Arjun needed acceleration, so the 1-year MBA became his rocket fuel.

    And Rohan? After weeks of reflection, he chose the 1-year MBA because he didn’t want to lose two years of corporate momentum. It turned out to be the best decision of his life.

    So the real question is — what stage are you in, and what do you value more: exploration or acceleration?


  • Top 3 Smartphones for Professionals Under ₹30,000 – Best Value in 2025

    Are you looking for a powerful, stylish, and future-ready smartphone under ₹30,000? In 2025, the mid-range smartphone market is more competitive than ever, and professionals now have flagship-level features at affordable prices. After careful research, here are the Top 3 Smartphones for Professionals Under ₹30,000 that balance performance, design, battery, and camera perfectly.


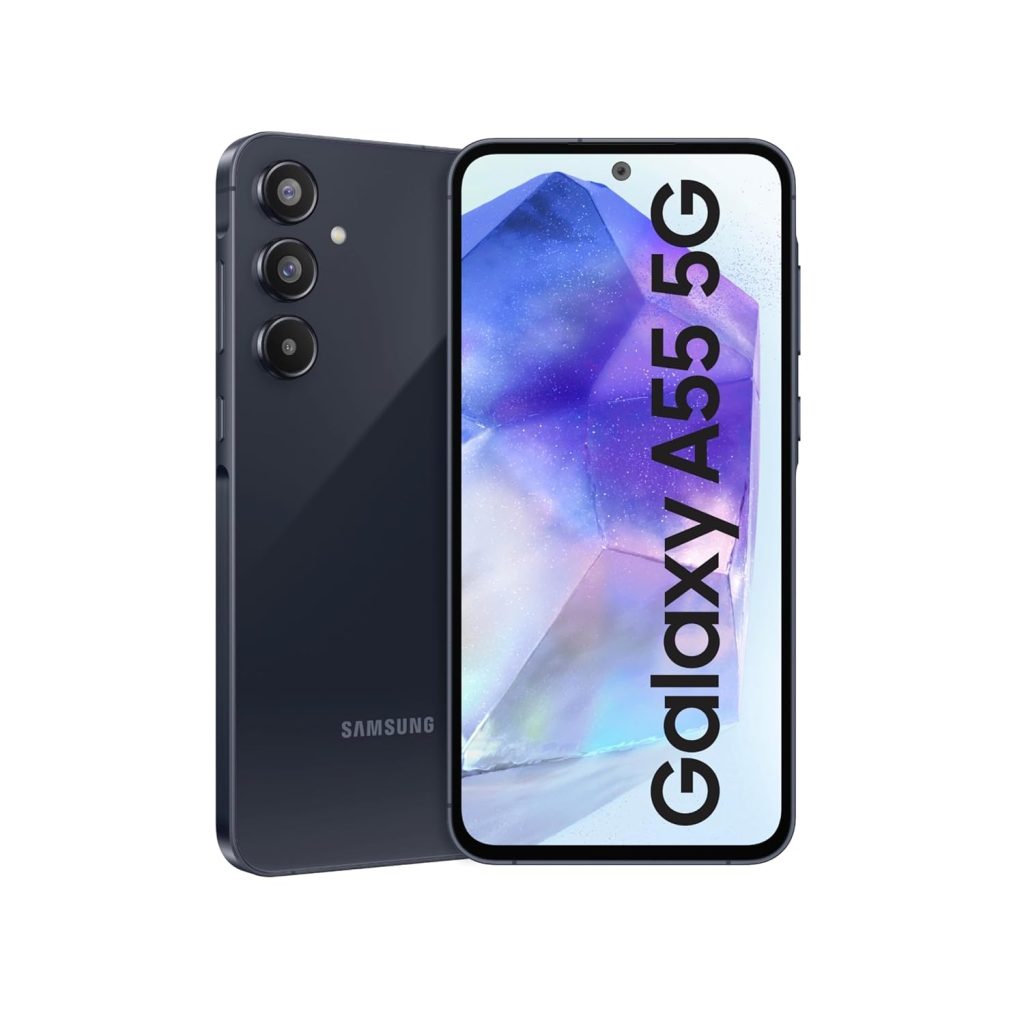
    1. Samsung Galaxy A55 5G (Awesome Navy, 8GB RAM, 256GB Storage)

    ➡️ Buy on Amazon – Samsung Galaxy A55 5G

    Price: ₹28,999 (MRP ₹45,999)

    Why Professionals Will Love It:

    • Premium Design: Metal frame, Gorilla Glass Victus+, and IP67 water/dust resistance.
    • Super AMOLED Display: 6.6” FHD+ with 120Hz refresh rate and Vision Booster for outdoor clarity.
    • AI Enhancements: Circle to Search, Object Eraser, AI photo editing.
    • Battery Life: Massive 5000mAh with 25W fast charging, lasting up to 2 days.
    • Software & Security: 4 OS upgrades, Samsung Knox defense-grade security, Samsung Wallet.
    • Performance: Exynos 1480 with vapor chamber cooling – smooth multitasking and no heating.

    Best For: Professionals who value premium build, security, long software support, and balanced performance without spending on a flagship.

    Top Review: “Possibly the best VFM phone from Samsung right now. Balanced in every way – display, battery, performance, and build.”


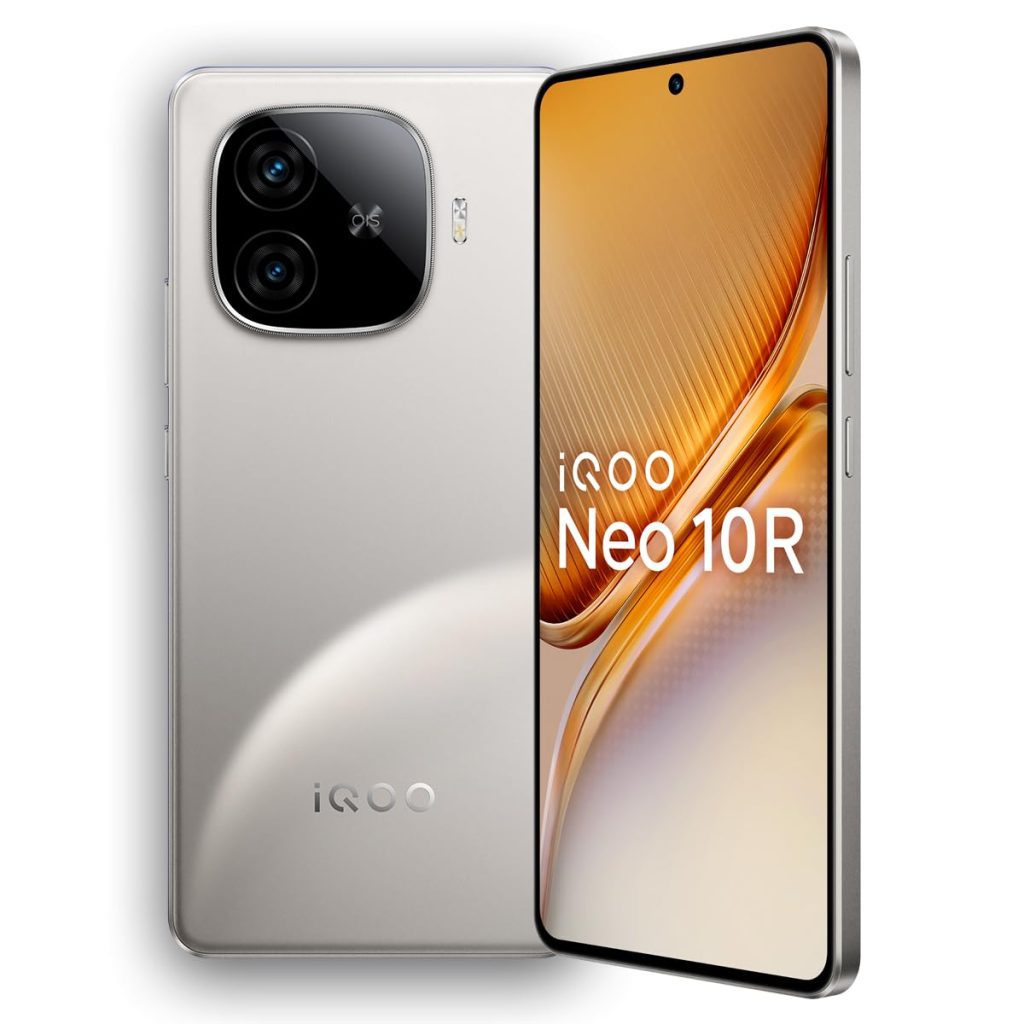
    2. iQOO Neo 10R 5G (Moonknight Titanium, 8GB RAM, 128GB Storage)

    ➡️ Buy on Amazon – iQOO Neo 10R 5G

    Price: ₹26,999 (MRP ₹31,999)

    Why Professionals Will Love It:

    • Flagship Processor: Snapdragon 8s Gen 3 with LPDDR5X RAM & UFS 4.1 (256GB variant).
    • Gaming Beast: Stable 90fps gaming, 2000Hz touch sampling, vapor chamber cooling.
    • Ultra-Slim Battery Phone: 6400mAh with 80W fast charging – slim yet long-lasting.
    • Camera Setup: 50MP Sony IMX882 OIS portrait + 8MP ultra-wide, 32MP selfie with 4K video.
    • AI Features: Instant Cut-out, AI Note Assist, AI Translation, AI Photo Enhance.
    • Software: Funtouch OS 15 (Android 15) with 3 years of Android & 4 years of security updates.

    Best For: Professionals who need top performance, gaming power, and long battery life – perfect for those balancing work and entertainment.

    Top Review: “Outstanding performance, amazing display, and strong battery backup. Perfect all-rounder under 27k.”


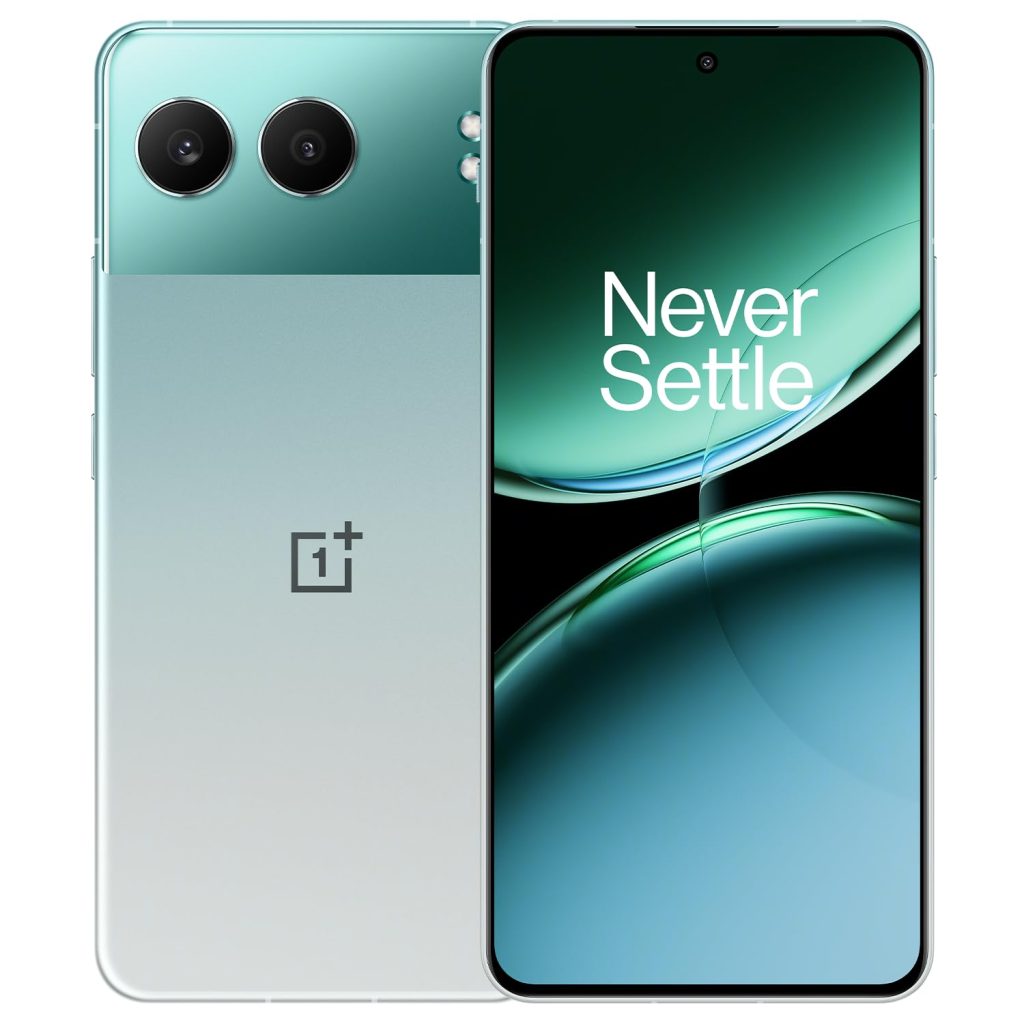
    3. OnePlus Nord 4 5G (Oasis Green, 8GB RAM, 256GB Storage)

    ➡️ Buy on Amazon – OnePlus Nord 4 5G

    Price: ₹27,999 (MRP ₹32,999)

    Why Professionals Will Love It:

    • Metal Unibody Design: Premium durability with TÜV SÜD rating.
    • Display: 6.74” AMOLED 120Hz with HDR10+ support – excellent for reading, streaming, and multitasking.
    • AI Productivity Tools: AI Best Face, AI Eraser, AI Summaries, AI Smart Cutout.
    • Battery & Charging: Huge 5500mAh battery with 100W SuperVOOC charging – full charge in ~28 mins.
    • Performance: Snapdragon 7+ Gen 3 with LPDDR5X RAM, smooth multitasking and moderate gaming.
    • Software: OxygenOS – clean, bloat-free, with 4 years of OS & 6 years of security updates.

    Best For: Professionals who want a sleek design, long battery life, and productivity-focused AI tools in a clean OxygenOS experience.

    Top Review: “Balanced performance, excellent build, and ultra-fast charging. A true professional’s phone.”


    📌 Final Verdict: Which One Should You Buy?

    • If you want premium design, long updates, and security: Go for Samsung Galaxy A55 5G.
    • If you want raw power, gaming stability, and ultra-slim design: Choose iQOO Neo 10R 5G.
    • If you want fast charging, AI productivity, and a clean software experience: Pick OnePlus Nord 4 5G.

    👉 All three are fantastic professional smartphones under ₹30,000 – it just depends on whether your priority is design & security, performance & gaming, or productivity & speed.

    Don’t wait too long – these deals may not last! Click the links below and grab your professional companion today:


  • Old Vehicles to Stay for 20 Years – But Be Ready for a Heavy Re-Registration Fee

    Ravi, a 48-year-old government employee in Lucknow, loves his old Maruti 800. It was his first car, bought back in 2004. Well-maintained, shining after every wash, and still giving 18 kmpl, Ravi never thought of parting ways with it.

    But last week, when he went to the RTO to ask about renewal after 20 years, he got a shock. The validity of his vehicle could be extended, yes—but the re-registration fee had now doubled. What was once a small amount has turned into a heavy financial burden.

    This is the reality for lakhs of vehicle owners after the central government’s new rule: vehicles can run for 20 years, but re-registering them beyond that will cost a lot more.


    What Has Changed?

    Earlier, most private vehicles were valid for 15 years, and renewal was possible for 5 more years with moderate fees. Now:

    • Vehicle life extended to 20 years (subject to fitness tests).
    • Re-registration fees doubled once the 20-year mark is crossed.

    New Fee Structure (Private Vehicles)

    Vehicle TypeOld Renewal FeeNew Renewal Fee
    Two-Wheelers₹1,000₹2,000
    Cars (LMVs)₹5,000₹10,000
    Three-Wheelers₹3,500₹5,000
    Imported Cars₹40,000₹80,000

    Story 1: Ravi’s Maruti 800 (2004 Model)

    • CTC (Total Cost of Car) then: ₹2.5 lakh
    • Current Market Value: Sentimental more than monetary (resale maybe ₹25,000)
    • Re-Registration Fee Now: ₹10,000

    👉 For Ravi, the irony is clear. The government fee for keeping the car on the road is almost half of what the car is worth today. He is now debating whether to scrap it, buy a small used Alto, or keep the 800 as a memory in his garage.


    Story 2: Priya’s Honda Activa (2005 Model)

    Priya, a school teacher in Pune, has been riding her Activa for almost two decades. It’s still reliable and used daily for 5–7 km trips.

    • Re-Registration Fee: ₹2,000
    • Market Value of Vehicle: Around ₹8,000–₹10,000

    👉 For Priya, paying 20–25% of the bike’s value just for registration feels unreasonable. She’s thinking of scrapping it and upgrading to an EV scooter with government subsidy benefits.


    Story 3: Arjun’s Imported Car

    Arjun, a businessman in Delhi, owns a 2003 Mercedes-Benz E-Class. He has kept it in pristine condition as a collectible.

    • Re-Registration Fee: ₹80,000 (up from ₹40,000)
    • Market Value: Still above ₹5–7 lakh for enthusiasts

    👉 For Arjun, the steep fee is still acceptable—because the car holds luxury and status value. But for average owners, these costs feel punishing.


    Why This Change?

    The government’s logic is simple:

    • Old vehicles pollute more.
    • Higher fees push people to scrap old cars and bikes.
    • Scrappage + purchase of new vehicles boosts the auto industry.

    What This Means for You

    1. Well-maintained but low-value vehicles: Renewal may not make financial sense. Example – 20-year-old bikes or entry-level cars.
    2. Sentimental vehicles: If you’re emotionally attached, be ready to spend more for keeping them on the road.
    3. Luxury and collectible vehicles: Owners will likely pay the higher fees without hesitation.
    4. Alternative: Instead of re-registering, scrapping gives you incentives like tax rebates and discounts on new vehicles.

    Final Thoughts

    For many Indian families, old vehicles aren’t just machines—they’re memories. First cars bought after years of savings, bikes that saw countless rides to college or work, and scooters that carried entire families.

    The new rule doesn’t stop you from keeping these vehicles, but it makes the decision more financially challenging.

    So, if your car or bike is nearing the 20-year mark, ask yourself:

    • Do I want to keep it at any cost?
    • Or is it wiser to let it go and invest in a cleaner, newer option?

    The answer may not just be about money—it might also be about your heart.

    Cost Comparison: Keep vs Buy New

    Vehicle TypeOld Vehicle (20+ yrs)New Vehicle (2025)Notes
    Bike (100–125cc)₹2,000 re-registration + ~₹5,000 yearly maintenance + low mileage (40 kmpl)₹80,000–₹1 lakh for new bike with warranty + 65 kmpl mileageNew bike pays back via fuel savings in 3–4 years
    Scooter (Activa class)₹2,000 re-registration + ~₹6,000 yearly maintenance + 35–40 kmpl₹1.2 lakh for new EV scooter (subsidy reduces cost)EV saves fuel costs completely
    Small Car (Alto, WagonR class)₹10,000 re-registration + ~₹12,000 yearly maintenance + mileage 14–16 kmpl₹4–5 lakh new car, 20 kmpl mileage + warrantyBetter resale, lower running cost
    Luxury/Imported Car₹80,000 re-registration + high maintenance (₹50,000+ yearly)₹40–60 lakh new luxury carFor collectors, renewal may still make sense

    Example:

    • Ravi’s Maruti 800 (2004) costs him ₹10,000 renewal + ~₹15,000 yearly upkeep. Over 5 years, that’s ~₹85,000—more than the resale value of the car.
    • If he buys a new Alto K10 at ~₹5 lakh, he gets warranty, higher mileage, and better safety.

    👉 For mass-market vehicles, buying new often makes more financial sense.
    👉 For collectors or sentimental owners, the higher fee is the “price of nostalgia.”


  • Income Tax Rules 2025: New ₹4 Lakh & ₹8 Lakh Limits on Perks – How They Boost Your Take-Home Salary

    Income Tax Rules Revised: New ₹4 Lakh & ₹8 Lakh Thresholds for Employee Perks

    The government has recently revised the income tax rules, bringing much-needed relief to salaried taxpayers. Two key thresholds have been significantly increased—one for classification of “specified employees” in relation to non-monetary perks, and the other for exemption on overseas medical treatment provided by employers. Let’s break down what these changes mean for you.


    1. Higher Limit for Tax-Free Non-Monetary Perks

    Earlier, employees earning more than ₹50,000 in salary could be classified as “specified employees,” making many employer-provided benefits taxable. This limit has now been raised to ₹4,00,000 per year.

    What does this mean?

    If your annual salary is ₹4 lakh or below, you will not be treated as a “specified employee.” As a result, certain non-monetary perquisites will not attract tax in your hands.

    Examples of such perks include:

    • Company-provided car with driver
    • Household help paid for by the employer
    • Educational facilities provided to children
    • Utility bills covered by the company
    • Transport facilities for daily commute

    This revision ensures that lower and middle-income employees can enjoy these benefits without worrying about additional tax liability.


    2. Overseas Medical Treatment Limit Increased to ₹8 Lakh

    The second big change relates to medical expenses borne by an employer for treatment abroad. Until now, only employees with a gross total income of up to ₹2 lakh could claim exemption. This threshold has now been raised to ₹8 lakh.

    Key points to note:

    • The exemption covers treatment, travel, and stay expenses (subject to RBI approvals).
    • The benefit can also extend to an attendant accompanying the patient.
    • Employees with gross total income up to ₹8 lakh can now avail this exemption.

    This change widens the relief net considerably, especially for families where overseas treatment is a necessity but the tax burden previously made it harder to manage.


    3. Who Still Needs to Pay Tax on Perks?

    Not every employee qualifies for these exemptions. Some cases where perquisites remain taxable include:

    • Company directors, irrespective of salary.
    • Employees with substantial ownership interest (20% or more voting power in the company).
    • Benefits such as stock options, free or concessional loans, club memberships, expensive gifts, and foreign travel reimbursements, which continue to be fully taxable.

    4. Why This Change Matters

    These revisions are part of the government’s push to modernize tax rules and bring them in line with current salary structures. The old limits had become outdated and were catching many low and middle-income employees in unnecessary taxation nets.

    Now, with a ₹4 lakh threshold for non-monetary perks and an ₹8 lakh limit for overseas medical perquisites, more salaried individuals will enjoy meaningful tax relief.


    5. Quick Summary

    Benefit TypeOld LimitNew LimitWho Gets Relief?
    Non-monetary perquisites (car, utilities, domestic help, etc.)₹50,000 salary₹4,00,000 salaryEmployees with annual salary ≤ ₹4 lakh
    Overseas medical treatment expenses₹2,00,000 gross income₹8,00,000 gross incomeEmployees with gross total income ≤ ₹8 lakh

    Final Thoughts

    For salaried taxpayers, these revisions are a welcome step that reduce tax burdens and provide better access to genuine employer-sponsored benefits. As always, proper documentation and accurate reporting in your income tax return will be essential to claim these exemptions smoothly.


    💼 Real-Life Salary Examples: Before vs After the New Tax Rules


    Example 1: Employee with ₹3.6 Lakh Annual Salary (₹30,000/month)

    This employee earns below the new ₹4 lakh threshold.

    Before the Change (Old Rules)

    • Basic Salary: ₹3,60,000
    • Perquisites (car + utilities covered by employer): ₹50,000
    • Total Taxable Income: ₹4,10,000 (Salary + Perks)

    👉 Since the old “specified employee” limit was only ₹50,000, the employee had to pay tax on all perks, pushing taxable income above exemption limits.

    Tax Payable (New Regime rates FY 2025–26): ~₹7,500


    After the Change (New Rules)

    • Basic Salary: ₹3,60,000
    • Perquisites (car + utilities): ₹50,000
    • Taxable Perquisites: Nil (Salary ≤ ₹4,00,000, hence not a specified employee)
    • Total Taxable Income: ₹3,60,000

    Tax Payable: Nil

    Savings due to new rules: ~₹7,500 (tax completely eliminated on perks).


    Example 2: Employee with ₹7.5 Lakh Annual Salary + Employer-Sponsored Medical Treatment Abroad

    This employee earns below the new ₹8 lakh threshold for medical perks.

    Before the Change (Old Rules)

    • Gross Salary: ₹7,50,000
    • Employer-paid Overseas Medical Expenses: ₹3,00,000
    • Old Exemption Limit: Only employees with income ≤ ₹2 lakh could claim exemption.
    • Result: Full ₹3,00,000 added to taxable income.

    Total Taxable Income: ₹10,50,000
    Tax Payable (New Regime): ~₹78,000


    After the Change (New Rules)

    • Gross Salary: ₹7,50,000
    • Employer-paid Overseas Medical Expenses: ₹3,00,000
    • New Exemption Limit: Employees with income ≤ ₹8 lakh qualify for exemption.
    • Result: Medical perks fully exempt.

    Total Taxable Income: ₹7,50,000
    Tax Payable (New Regime): ~₹39,000

    Savings due to new rules: ~₹39,000


    📊 Quick Comparison

    ScenarioOld Rules (Taxable Income)Tax PayableNew Rules (Taxable Income)Tax PayableSavings
    ₹3.6 L salary + ₹50k perks₹4.1 L₹7,500₹3.6 LNil₹7,500
    ₹7.5 L salary + ₹3 L medical₹10.5 L₹78,000₹7.5 L₹39,000₹39,000

    ✅ Key Takeaway

    • Employees with salary up to ₹4 lakh now get a big relief from taxation of non-monetary perks.
    • Employees with gross income up to ₹8 lakh can now enjoy tax-free employer-sponsored overseas medical treatment.
    • These changes put more money back in the pockets of middle-income earners and simplify compliance.

    Disclaimer: This article is for educational purposes only. Taxpayers should consult a qualified tax professional or financial advisor for personalized guidance before making financial or tax-related decisions.